Correlation between BM&FBOVESPA stock returns: an analysis via dynamic copula
DOI:
https://doi.org/10.29327/2520355.11.2-2Keywords:
Copulas, stock returns, correlationAbstract
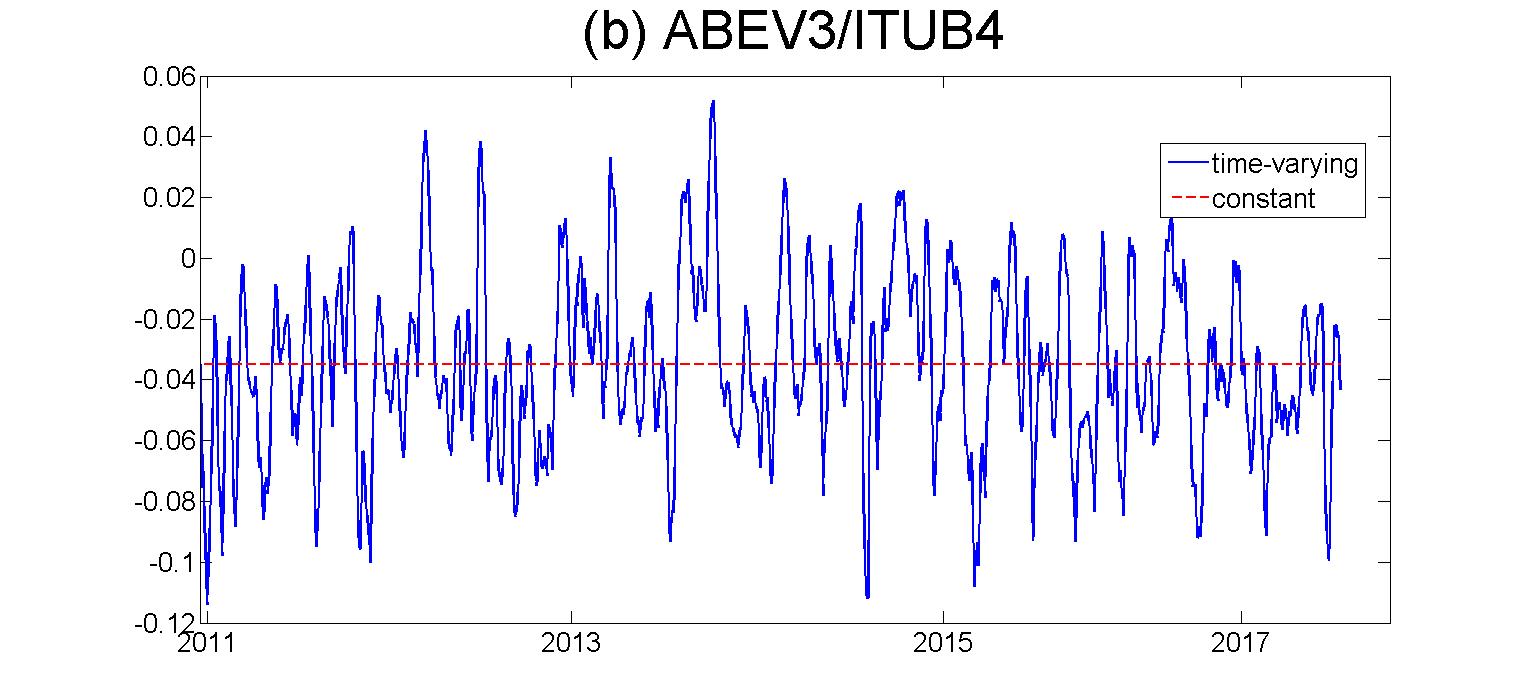
The behavior of the dependence among returns on financial assets is important for the understanding of finance issues. In this context, the dynamic copulas theory is an important tool in the multivariate analysis of financial series, thanks to its flexibility to construct multivariate distribution functions that reproduce several types of dependencies and measure the movement of this relationship over time. In this way, this work aims to investigate and measure the structure and the movement of the correlation between pairs of stock returns referring to the companies Ambev, Ita ́u Unibanco, Petrobras listed on the São Paulo Stock Exchange (BM&FBOVESPA) at the period from January 3, 2011, to June 21, 2017. For this, he used the conditional copula Normal with time-variant parameter specified by Patton (2006) that quantifies and captures the temporal trajectory of the linear correlation coefficient, which configures a relevant measure of dependency. The results of the magnitude of the dependence and the trajectory over time measured between these pairs of stocks reflect the peculiarities of the sectors of performance of each company, as well as the influence of market uncertainty, which demonstrates the importance of the diversification of assets in investment analysis.
References
DING, Z.; GRANGER, C. W. J.; ENGLE, R. F. A long memory property of stock market returns and a new model. Journal of Empirical Finance, v. 1, n. 1, p. 83-106, 1993.
ENGLE, R. F. Autoregressive conditional heteroscedasticity with estimates of the variance of United Kingdom inflation. Econometrica, v. 50, n. 4, p. 987-1007, 1982.
GHALANOS, A. rugarch: Univariate GARCH models. R package version 1.3-8. 2017.
JOE, H., & XU, J. J. The estimation method of inference functions for margins for multivariate models. Technical Report no. 166. Department of Statistics, University of British Columbia, Vancouver, 1996.
LACERDA, A. C. D. Dinâmica e evolução da crise: discutindo alternativas. Estudos Avançados, v.31, n.89, p. 37-49, 2017.
MARKOWITZ, H. Portfolio selection. The Journal of Finance, v. 7, n. 1, p. 77-91, 1952.
PATTON, A. J. Modelling asymmetric exchange rate dependence. International Economic Review, v. 47, n. 2, 2006.
SKLAR, A. Fonctions de répartition et leurs marges. Publications de la Institut de Statistique de la Université de Paris, 8, 229-231. 1959.
R CORE TEAM. R: A language and environment for statistical computing. R Foundation for Statistical Computing, Vienna, Austria. 2019. ISBN 3-900051-07-0, URL http://www.R-project.org/.
Downloads
Published
Issue
Section
License
Proposta de Política para Periódicos de Acesso Livre
Autores que publicam nesta revista concordam com os seguintes termos:
- Autores mantém os direitos autorais e concedem à revista o direito de primeira publicação, com o trabalho simultaneamente licenciado sob a Licença Creative Commons Attribution que permite o compartilhamento do trabalho com reconhecimento da autoria e publicação inicial nesta revista.
- Autores têm autorização para assumir contratos adicionais separadamente, para distribuição não-exclusiva da versão do trabalho publicada nesta revista (ex.: publicar em repositório institucional ou como capítulo de livro), com reconhecimento de autoria e publicação inicial nesta revista.
- Autores têm permissão e são estimulados a publicar e distribuir seu trabalho online (ex.: em repositórios institucionais ou na sua página pessoal) a qualquer ponto antes ou durante o processo editorial, já que isso pode gerar alterações produtivas, bem como aumentar o impacto e a citação do trabalho publicado (Veja O Efeito do Acesso Livre).